How Remittances Help Albanian Businesses Grow
How Remittances Help Albanian Businesses Grow
Remittances are one of the main pillars of the Albanian economy, supporting 23% of households and accounting for 13% of GDP. They provide a direct source of financing for small and family-run businesses, often easier and faster to obtain than bank loans or foreign direct investment (FDI).
Key points:
Total value: $2.34 billion USD (2023).
Use: Opening small businesses (shops, restaurants) and investing in agriculture.
Challenge: 37% of remittances arrive outside formal channels, making them harder to monitor.
Comparisons: Remittances are more accessible to households, while FDI and bank loans focus on larger projects and come with stricter conditions.
Bottom line? Remittances are a valuable source for local economic development, but maximizing their impact requires better financial management and more strategic use.
1. Remittances
Remittances are an important source of financing for Albanian businesses, providing direct capital without the usual bureaucracy of lending. These funds support families and entrepreneurs, driving economic development.
Accessibility and Ease of Use
One of the main advantages of remittances is that they are easily accessible. Unlike bank loans, remittances reach families directly without complicated conditions, making them especially useful for those who are just starting a business.
"Remittances ease credit constraints and provide risk insurance, which supports small enterprises, entrepreneurial skills and possibly a temporary fall in production." - Bimal Ghosh
This makes remittances an important support for family businesses and small enterprises, which are the backbone of the Albanian economy.
Key Investment Sectors
Remittances have had an impact on many economic sectors. Families often use these funds to open small businesses, such as shops and restaurants, or to invest in agriculture by building greenhouses and upgrading production equipment.
The Role of Financial Safety Net
Beyond investment, remittances serve as a safety net for individuals who want to take entrepreneurial risks. These funds have helped reduce poverty by 8 percentage points. Moreover, remittances improve living conditions and consumers' purchasing power, creating a positive effect on the local economy.
Challenges and Limitations
Despite their many benefits, remittances face several challenges. Around 37% of funds are sent in cash, outside formal channels, which makes them difficult to monitor. Prime Minister Edi Rama has noted that remittances from emigrants are declining every year, underscoring the need for other financial sources. Nevertheless, thanks to their stability and broad economic impact, remittances remain an important source alongside tourism and foreign direct investment.
Development Potential
To increase the impact of remittances on Albanian businesses, it is essential to improve financial infrastructure and raise awareness about financial management. Currently, only 44.17% of adults in Albania have a bank account. When used carefully and strategically, remittances can help develop small and medium-sized enterprises, contributing to a more diversified economy and the creation of new jobs. These benefits put remittances in a strong position to be compared with other financial sources such as bank loans and foreign direct investment.
2. Foreign Direct Investment (FDI)
Foreign Direct Investment (FDI) is an important source of financing for the Albanian economy, bringing not only capital but also new technology and experience. Unlike remittances, which often support the household economy, FDI brings investors with a long-term vision, offering a different approach to economic development.
Performance and Current Trends
In 2023, FDI inflows reached USD 1.6 billion, while total accumulated investment exceeded USD 14 billion. In 2024, there was a 5.6% increase, reaching €1,583 million from €1,499 million the previous year. Reinvested earnings also rose by 6.2%, reaching €853 million, a clear indicator of investor confidence in the future.
Key Sectors and Sources of Investment
FDI has focused mainly on a few key sectors:
Real estate: 22% of 2023 flows.
Extractive industries: 18%.
Banking and insurance: 16%.
Energy: 11%.
Meanwhile, Switzerland, the Netherlands, Canada, Italy, Turkey and Austria are among the main countries contributing to Albania's FDI. Moreover, investment from the United States has risen markedly, reaching USD 300 million at the end of 2023, up from just USD 100 million in 2020.
Advantages and Economic Impact
FDI brings more than money: it brings new technologies and management practices that help improve the country's efficiency and competitiveness. In addition, these investments create jobs and contribute to infrastructure development, such as transport networks and energy systems.
"The government has worked diligently to create a welcoming environment for everyone, from tourists to major investors. For many, engaging with Albania has proven both rewarding and inspiring." - Igli Hasani, Albania's Minister for Europe and Foreign Affairs
Challenges and Barriers
However, FDI does not come without challenges. Albania is often perceived as a difficult place to do business because of corruption, the informal economy and weak contract enforcement. In 2023, the country ranked 98th out of 180 countries in the Corruption Perceptions Index. Another problem is the emigration of skilled labor, which creates gaps in the labor market and negatively affects the ability to attract investors.
Accessibility for Small and Medium-Sized Businesses
Unlike remittances, which directly help families and small businesses, FDI usually focuses on large projects. This makes it harder for Albanian small and medium-sized businesses to benefit from it. Moreover, equity investment fell by 3.5% in 2024, showing that the entry of new investors into the market is still limited.
Sustainability and Long-Term Outlook
FDI is an important indicator of investor confidence in a country. Currently, the main focus remains on traditional sectors, such as energy and construction, while newer, high-potential sectors remain underdeveloped. To attract new investment and create a more favorable climate, Albania must take concrete steps to improve the business environment and attract new capital.
3. Bank Lending
Bank lending is a classic source of financing that presents distinct challenges compared with remittances and foreign direct investment (FDI). In this section, we will examine its role in the development of Albanian businesses and how it compares with other sources of financing.
Current State of the Banking Market
The banking system in Albania is going through a phase of consolidation, which aims to increase competition and improve banking services for citizens and businesses. Despite this, the pace of lending remains low, mainly because of strict lending standards and weak demand from the private sector. Currently, credit to the private sector accounts for only 33% of GDP, a much lower figure than the over 50% seen in other countries in the region.
In 2023, this indicator stood at just 30.6% of GDP, placing Albania at the bottom of the regional list. This reflects the conservative approach of Albanian banks, particularly when it comes to financing small and medium-sized businesses, which often face major barriers to obtaining loans.
Challenges for Small and Medium-Sized Businesses
Small and medium-sized enterprises (SMEs) are among those most affected by difficulties in accessing finance, which limits their opportunities for growth. For example, 16% of small enterprises and 34% of medium-sized ones report that financing is one of the main obstacles to their development. Moreover, fewer than 20% of small rural enterprises have access to bank loans or a line of credit.
Some of the main obstacles for these businesses include:
High collateral requirements: In 2019, banks required collateral worth 177% of the requested loan amount.
Complex processes: Procedures are often unclear and involve unjustified fees, making the process even harder.
High interest rates: Micro and small businesses often face high interest rates and collateral that exceeds the value of the loan.
These financial barriers negatively affect the resilience and development of these businesses, limiting their economic potential.
Impact on Business Resilience
Difficult lending conditions have a direct impact on the stability and growth of businesses in Albania. The financing gap for SMEs in the country is estimated at around 9% of GDP, showing that many businesses fail to realize their potential because of a lack of financing. Moreover, around 80% of business investment is financed from internal sources, including personal funds and family remittances.
Initiatives for Improvement
To address these challenges, the Albanian government has established the New Albanian Development Bank, which aims to close the financing gap for SMEs and startups. The government has committed ALL 10 billion in capital to this bank over a four-year period.
Another positive example is the cooperation between the Council of Europe Development Bank and ProCredit Bank Albania. In 2021, the Council of Europe approved a loan of €15 million to ProCredit Bank Albania, aimed at long-term financing for SMEs in sectors such as trade and manufacturing. This initiative is expected to support around 100 projects.
Digital Transformation and Outlook
The banking sector in Albania is undergoing a significant digital transformation. However, obstacles such as low levels of digital literacy, a preference for cash transactions and cybersecurity risks remain problematic. Although 93% of banks have set up digital departments, only 68.19% of assets show limited engagement in this direction.
Bank lending remains an important source of financing, but the existing challenges call for deep reforms to improve access and support the development of Albanian businesses.
Advantages and Disadvantages
To understand the impact of remittances on the development of Albanian businesses, it is important to examine three main sources of financing: remittances, foreign direct investment (FDI) and bank lending. Each has characteristics that affect enterprise growth differently. The comparison below helps assess the strengths and limitations of each source.
Comparison of Financing Sources
Criteria | Remittances | Foreign Direct Investment (FDI) | Bank Lending |
|---|---|---|---|
Accessibility | High – around 40% of the population has ties to emigrants | Varies depending on investment policies | Limited, especially for small businesses |
Cost | No direct cost, owing to their family nature | Has indirect costs and investment conditions | High because of interest rates and collateral requirements |
Stability | Relatively stable | Sensitive to global crises | Varies depending on economic conditions |
Size of Funds | Suited to small enterprises | High, for large projects | Moderate, depending on the bank's capacity |
Control | Full control by the family | May involve outside influence | Control after receiving the loan, with some restrictions |
This comparison helps assess which source of financing is best suited to the different needs of businesses.
Advantages of Remittances
Remittances are an important source of financing for small enterprises. They provide stability for businesses and help mitigate financial risks. They are often used to open businesses in sectors such as retail and hospitality, including shops, bars, restaurants and hotels. Moreover, remittances have a positive effect on the economy, helping to create new jobs.
Disadvantages of Remittances
However, remittances have limitations. The size of the funds is usually small, limiting the ability to finance large projects. Moreover, the flow of remittances is affected by external factors, such as the economic situation in host countries and emigration policies, which makes them unpredictable.
Advantages of Foreign Direct Investment (FDI)
FDI brings large funds and creates opportunities for major development projects. Alongside capital, it offers access to advanced technology, expertise and international markets, giving the economy an important boost.
Disadvantages of Foreign Direct Investment (FDI)
On the other hand, FDI can create challenges. Competition to attract investment often leads to a lowering of local standards. Moreover, foreign investments are sensitive to global crises, and investors may suddenly withdraw, leaving projects unfinished.
Advantages of Bank Lending
Bank lending is a useful option for long-term financing. It offers flexibility in the use of funds and is a good solution for businesses that meet the required criteria.
Disadvantages of Bank Lending
However, lending comes at a high cost. Interest rates and collateral requirements are often an obstacle for small businesses. According to the data, 16% of small businesses and 34% of medium-sized ones consider financing one of the main challenges, while the financing gap for these businesses is estimated at around 9% of GDP.
Conclusion
The analysis of the main sources of financing highlights the features that set remittances apart from foreign direct investment (FDI) and bank lending. While FDI reached almost USD 1.6 billion in 2023 and is suited to large projects, remittances emerge as a more accessible and more stable source, especially for family businesses. These findings encourage enterprises to use remittances more effectively, giving priority to economic development.
Prime Minister Edi Rama has stressed the importance of making use of domestic resources to drive economic growth:
So we have turned toward the country's potential and its great resources, and we use them in a way that they produce growth and prosperity.
One of the main challenges remains the high cost of remittances. For example, to send USD 200 to Albania, the average cost reaches 8.7%. Using digital channels can help reduce these expenses, especially when 37% of remittances are still carried in physical form. Technology has the potential to simplify this process and make remittances more affordable.
Another important step is financial education. By focusing on households that receive remittances, educational programs can help turn these funds from a source of consumption into an investment tool. This transformation can support the development of small businesses and create a more lasting impact on the local economy.
Moreover, remittances offer particular stability during periods of economic instability, making them a reliable source for sectors such as retail, hospitality and agriculture. By contrast, FDI is more sensitive to global fluctuations. This stability makes remittances a suitable choice for small businesses seeking financial security.
Based on this analysis, Albanian businesses can benefit from a balanced approach. Remittances can be used to start small businesses, while combining them with bank loans or foreign direct investment offers opportunities for greater growth. This combination not only reduces dependence on a single source but also creates a more solid foundation for economic development.
Challenges Albanian Businesses Face in Using Remittances
Businesses in Albania face several obstacles when trying to use remittances as a source of financing. One of the main problems is the lack of consistent stability, as remittances are often unpredictable and cannot be guaranteed as a regular source of income.
Another difficulty stems from the fact that most remittances are used to cover family needs and daily expenses, leaving little room for business investment. Moreover, businesses often encounter limitations in access to long-term loans, making it difficult to use remittances for expansion or to bring new ideas to market.
To cope with these challenges, it is vital that enterprises have access to financial advice and support networks. Organizations such as Business Network Albania offer valuable help to Albanian entrepreneurs, guiding them on how to manage their resources more strategically and effectively.
×How can remittances be better managed to support economic development in Albania?
Improving the Financial Management of Remittances
To manage remittances better and increase their impact on the Albanian economy, here are a few steps that can make a big difference:
Reducing transfer costs: Fees for international remittances are often high. Partnerships with more efficient financial service providers can help reduce these costs, leaving more money in the hands of the families who receive it.
Financial education: Many families and individuals are unaware of ways to invest or save remittances. Through educational programs, they can learn how to use these funds for long-term benefits, such as investing in education, property or businesses.
Expanding financial infrastructure: By providing broader access to banking services and financial technologies, remittances can be used more strategically. For example, digital platforms can simplify the remittance process and increase transparency.
These improvements not only affect the financial empowerment of individuals and families, but also create new opportunities for Albanian businesses, helping the country's economic development.
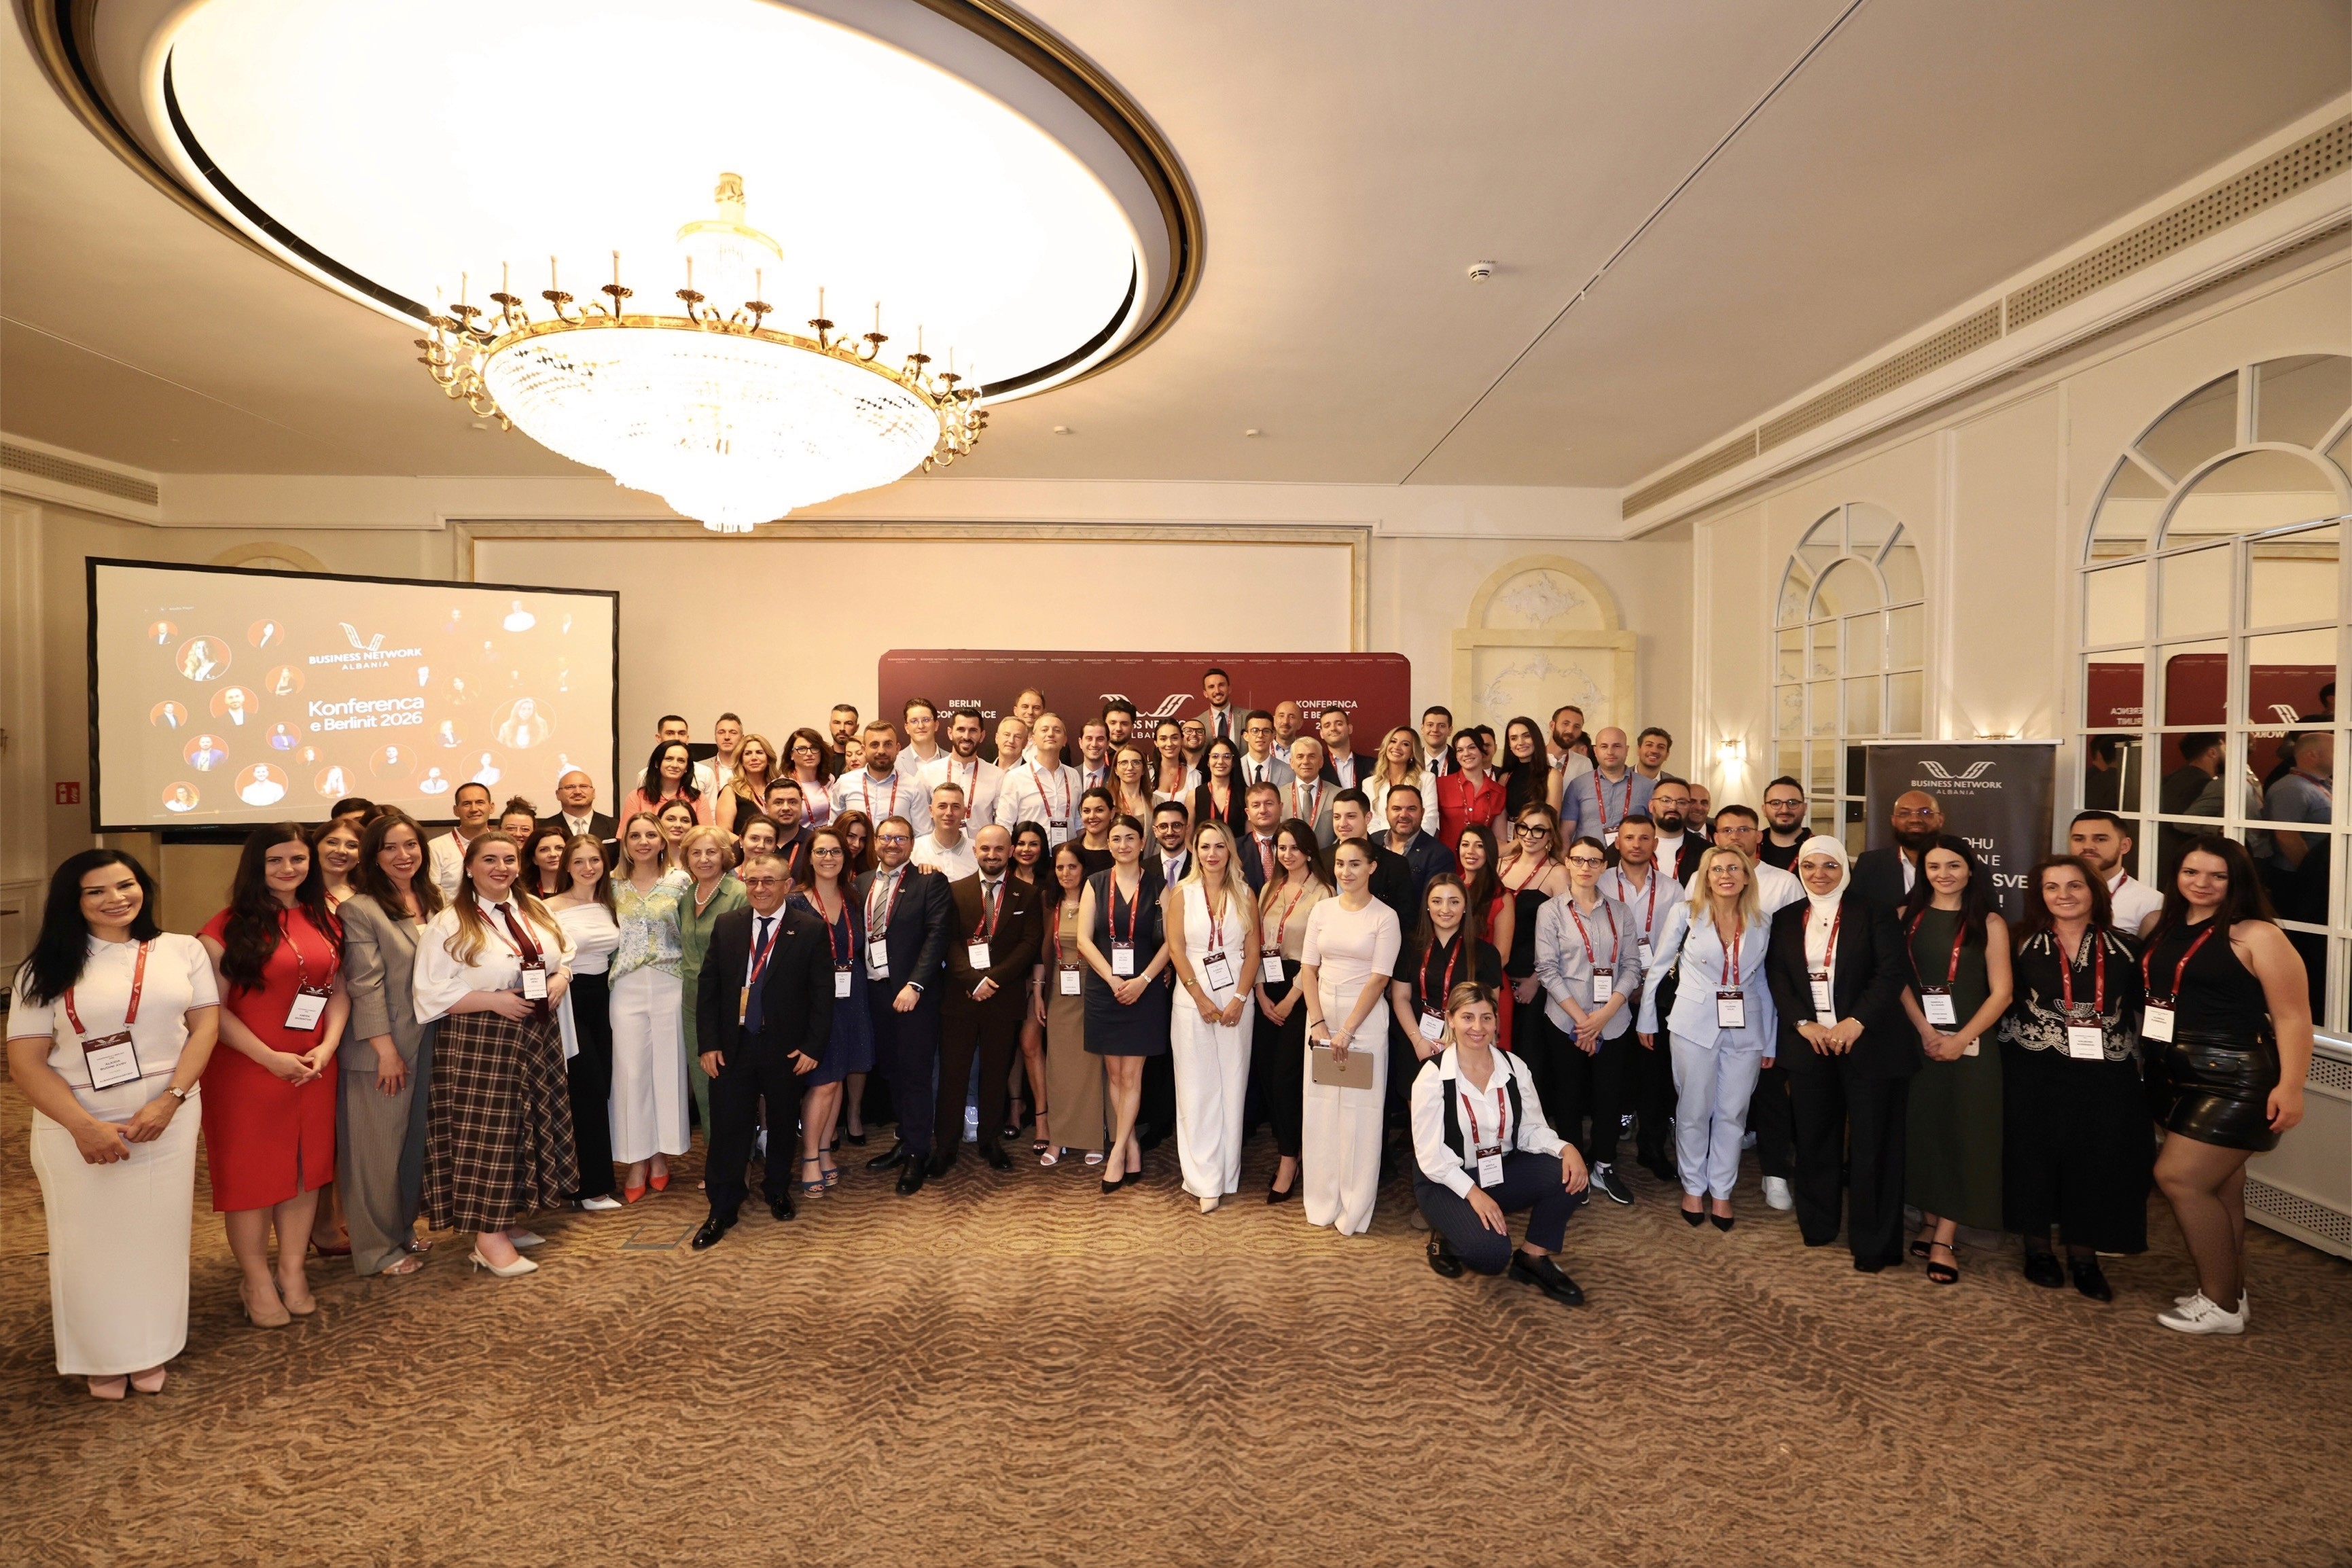
BNA marked another success with its conference in Berlin.
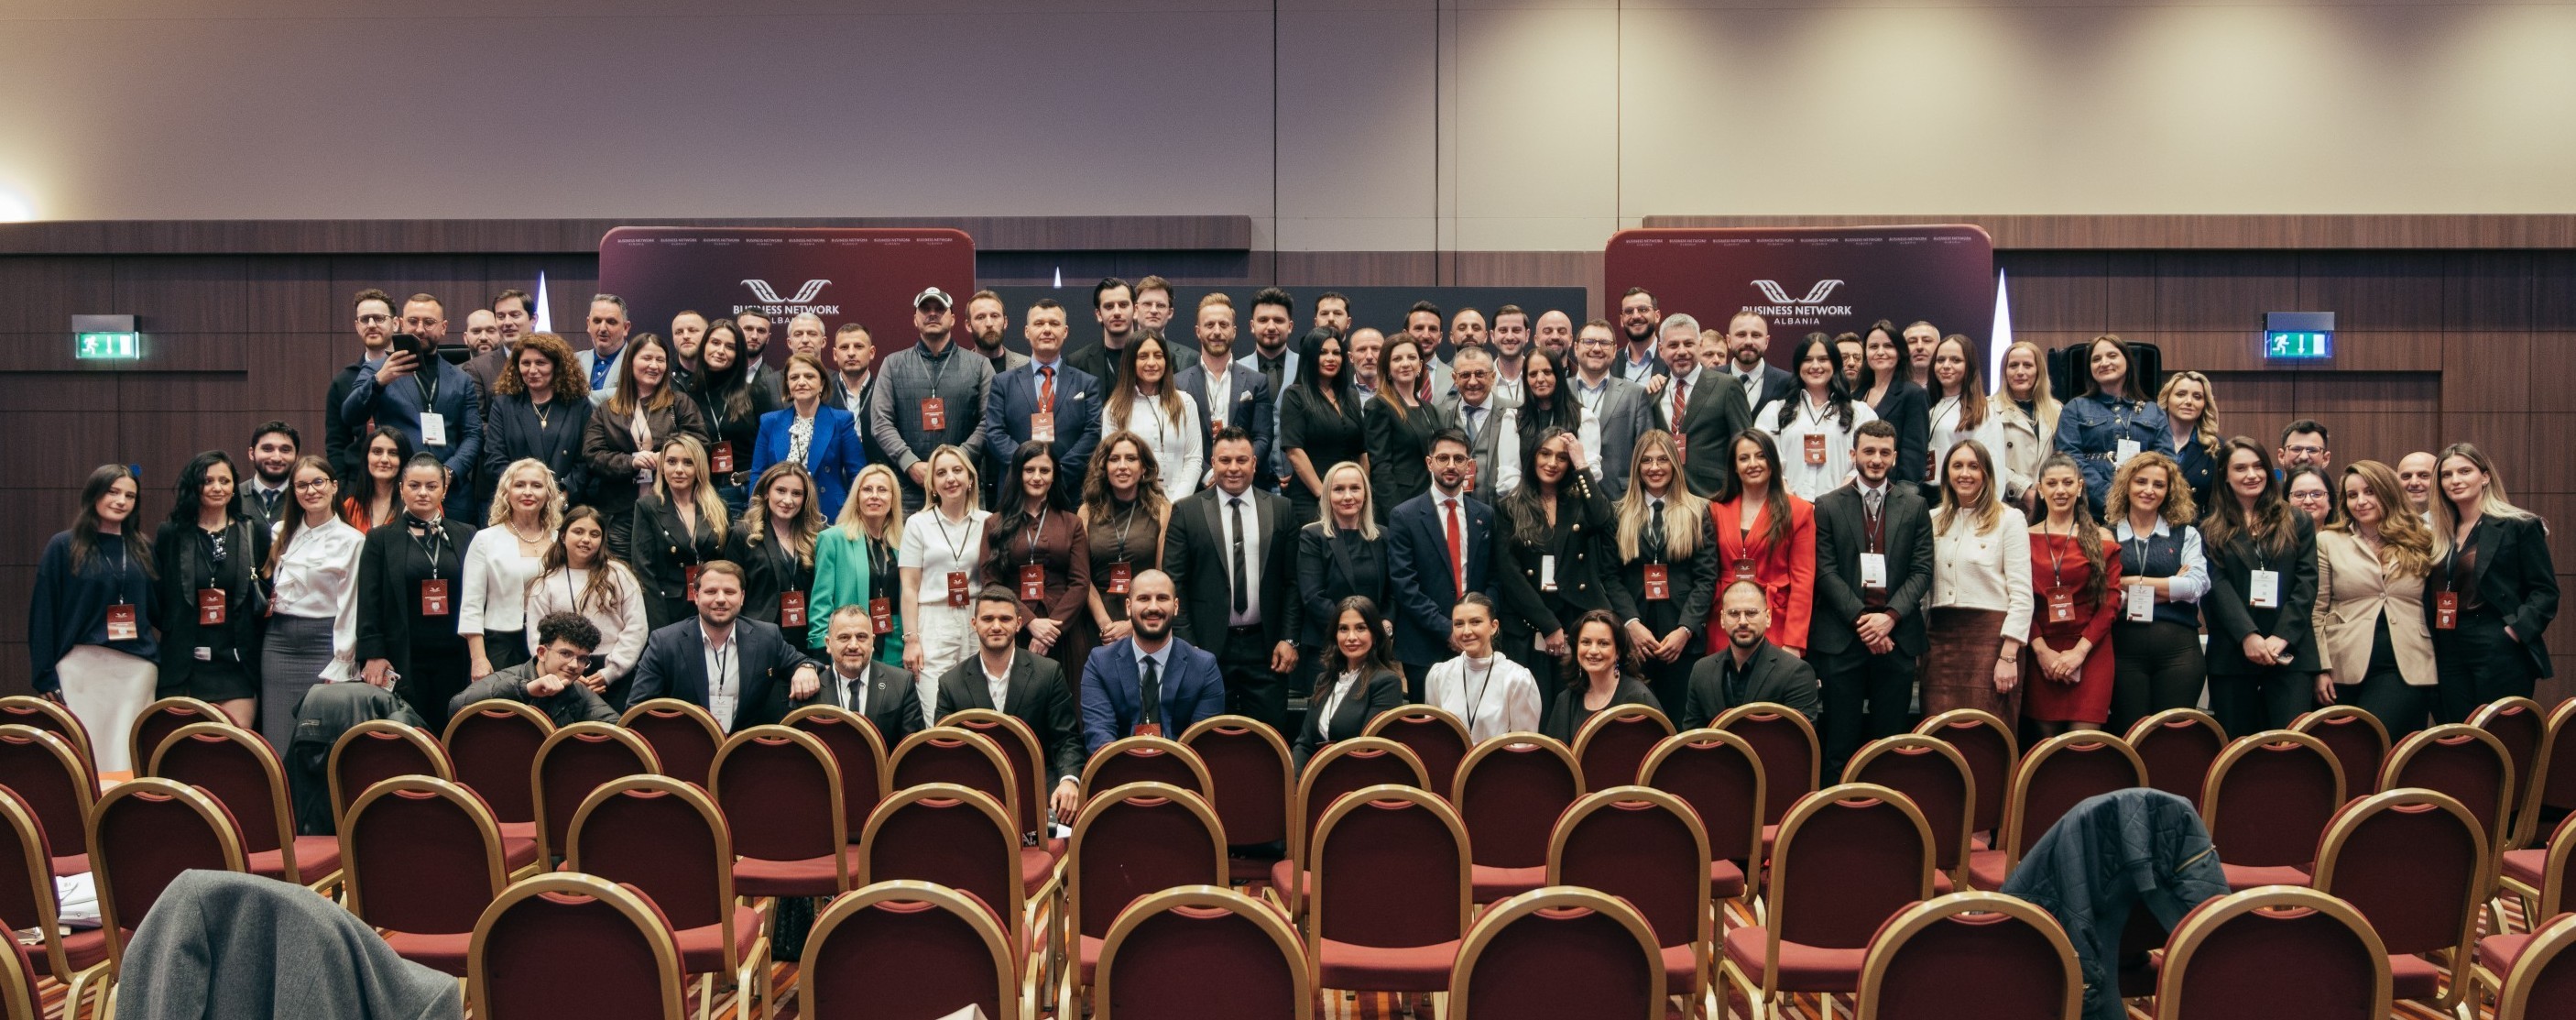
London Economic Conference 2026 – International Cooperation in Great Britain
Overview of Albanian Business 2025–2026: From Survival to Growth with Intelligence
Ready to join our ecosystem?
Over 215 Albanian members around the world have chosen to be part of BNA.
Join BNA